The relationship between substantive intellectual property law and fiscal legislation is often overlooked until a seemingly routine procedural requirement becomes the subject of litigation. A recent decision of the Kerala High Court brings this intersection into sharp focus.
In John Vadassery v. Registrar of Trade Marks & Anr., W.P.(C) No. 17 of 2026, decided on 30 September 2026, Justice Bechu Kurian Thomas considered whether an authorisation executed in favour of a trademark agent under Section 145 of the Trade Marks Act, 1999, read with Rule 19 of the Trade Marks Rules, 2017, is liable to stamp duty.
The petitioner, himself a trademark agent, challenged the insistence of the Trade Marks Registry that an authorisation empowering a trademark agent to act before the Registry should be stamped as a power of attorney. His central submission was that Section 145 speaks only of a person being “duly authorised” and does not require a power of attorney. Since Rule 19 prescribes the manner of authorisation through Form TM-M, it was argued that an authorisation on the prescribed form should suffice without attracting stamp duty.
The Kerala High Court rejected that contention.
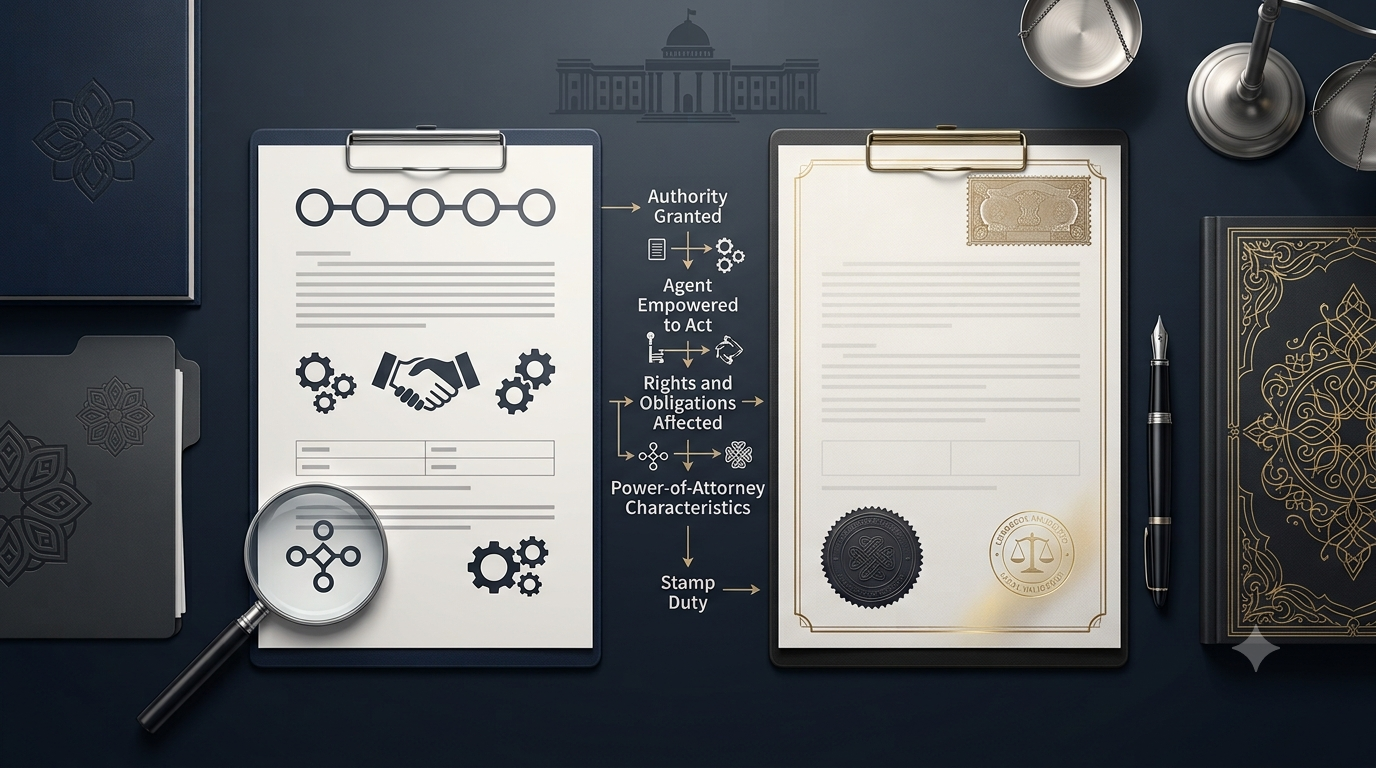
The Court held that the statutory authorisation contemplated under Section 145, read with Rule 19, is an instrument creating a right in the authorised person to represent another, and that such an instrument possesses the essential characteristics or “trappings” of a power of attorney. Consequently, it is liable to stamp duty under the applicable Stamp Act in the State where it is executed.
The judgment is significant because it draws a careful distinction between the law governing representation before the Trade Marks Registry and the law governing fiscal liability on the instrument by which such representation is created.
The Question Before the Court
The writ petition raised two closely connected questions:
- Whether an authorisation filed by a trademark agent under Section 145 of the Trade Marks Act is liable to payment of stamp duty; and
- Whether such an authorisation can be treated as a power of attorney for the purposes of stamp legislation.
The controversy arose from the Registry’s insistence that applicants represented by trademark agents submit an authorisation stamped as a power of attorney.
The petitioner contended that this requirement had no statutory basis.
His argument proceeded from the language of Section 145 itself. The provision permits certain acts required to be performed before the Registrar to be performed by a person “duly authorised in the prescribed manner”, including a legal practitioner, a registered trademark agent, or a person in the sole and regular employment of the principal.
The petitioner emphasised that Parliament had deliberately used the expression “authorised”, rather than “power of attorney”. According to him, the distinction was substantive and not merely semantic.
Rule 19 of the Trade Marks Rules, 2017, further provides the mechanism for such authorisation and prescribes Form TM-M.
The petitioner’s case, therefore, was that once the statute and rules prescribe the form and manner of authorisation, the Registry could not superimpose a requirement that the document be stamped as a power of attorney.
The Court, however, approached the issue from a different statutory perspective.
Section 145 Does More Than Permit Appearance
The Court first examined the actual legal effect of an authorisation under Section 145.
Section 145 permits a person to act before the Registrar through an authorised representative. Rule 19 prescribes the form in which such authorisation is to be executed and also provides that service upon the authorised agent is deemed to constitute service upon the person who has given the authorisation.
The Court found that the consequences of such authorisation are considerably broader than a mere permission to make an appearance.
The authorised person can:
- act on behalf of the principal before the Trade Marks Registry;
- receive notices and communications;
- accept service of documents;
- appear in proceedings before the Registrar; and
- undertake various acts relating to trademark applications and proceedings.
The Court emphasised that the role of a trademark agent is therefore “multifarious” and significant.
This assumes particular importance because proceedings before the Trade Marks Registry are capable of affecting substantive trademark rights. Applications for registration, oppositions and other proceedings may determine whether a proprietary interest in a mark is acquired, challenged, restricted or otherwise affected.
Thus, the Court reasoned that the acts of the agent do not merely have procedural significance. They can bind the principal and can create or affect rights.
That legal effect was central to the Court’s conclusion.
The Trade Marks Act Cannot Determine Stamp-Duty Liability
One of the most important doctrinal observations in the judgment is that the question of stamp duty cannot be answered merely by looking at the Trade Marks Act and the Rules framed under it.
The petitioner had relied substantially upon the fact that neither Section 145 nor Rule 19 expressly states that the authorisation must be stamped.
The Court rejected the premise that such silence resolves the issue.
Justice Bechu Kurian Thomas observed that stamp duty is a fiscal measure. Its imposition flows from the applicable Stamp legislation, whose object is to secure revenue on specified classes of instruments.
Consequently, the Trade Marks Act cannot control or determine whether stamp duty is payable on a particular document.
This distinction is doctrinally important.
The Trade Marks Act answers one question:
What authorisation is necessary for a person to represent another before the Registrar?
The applicable Stamp Act answers another:
Does the document creating that authority constitute a taxable instrument?
The two statutes operate in different fields.
The fact that Rule 19 prescribes a particular form of authorisation therefore does not immunise that document from fiscal consequences under stamp legislation.
“Authorisation” Versus “Power of Attorney”: Substance Over Label
The petitioner’s strongest argument was perhaps linguistic: the statute calls the document an “authorisation”, not a “power of attorney”.
The Court declined to treat nomenclature as determinative.
This reflects a broader principle of statutory interpretation: the legal character of an instrument depends upon its substance and operative effect, rather than merely the label assigned to it.
The Kerala Stamp Act defines an “instrument” broadly to include every document by which a right or liability is, or purports to be, created, transferred, limited, extended, extinguished or recorded.
The definition of “Power of Attorney” similarly encompasses an instrument empowering a specific person to act for and in the name of the person executing it.
Against that statutory framework, the Court found that the authorisation under Section 145 read with Rule 19 is not a merely administrative piece of paper.
It creates a legally operative authority in favour of another person.
Once the document empowers the trademark agent to act for and represent the principal before the Registry, it falls within the conceptual and statutory characteristics of a power of attorney.
The Court therefore concluded that the document must be stamped under the applicable Stamp Act where it is executed.
Why the Registrar’s Status Matters
Another important aspect of the judgment concerns the distinction between the Trade Marks Registry and a Court or Tribunal.
The Court noted that the Registrar of Trade Marks is an officer appointed by the Central Government and is neither a Court nor a Tribunal.
This distinction became relevant because the petitioner sought to draw an analogy with documents filed before courts.
The Court explained that an advocate’s vakalatnama may, in substance, operate as a power of attorney. However, when filed before a Court or Tribunal, the applicable court-fee legislation may govern the document. In such circumstances, the statutory treatment of the document under court-fee legislation can affect whether stamp duty is additionally attracted.
That reasoning could not be transplanted to an authorisation filed before the Trade Marks Registry.
Since the Registrar is not a Court or Tribunal, the Kerala Court Fees and Suits Valuation Act, 1959 does not govern documents presented before the Registry in the same manner.
Consequently, the Court found no basis for treating trademark-agent authorisations as exempt from stamp duty on the analogy of court filings.
The Significance of Institute of Chartered Accountants of India v. Union of India
The Court also relied upon an earlier decision of the Kerala High Court in The Institute of Chartered Accountants of India v. Union of India, reported at 2002 SCC OnLine Ker 675.
That case concerned authorisations filed before taxing authorities.
The Court had there considered the nature of authorisations enabling representatives to appear before statutory authorities and concluded that such authorisations were liable to be stamped under the applicable Stamp Act where executed.
The principle was considered applicable in the present context.
The analogy is instructive.
A statutory authority may not be a conventional civil court, but an authorisation empowering a professional to act on behalf of another before that authority can nevertheless constitute an instrument creating legal authority.
The fiscal consequence follows from the character of the instrument, not from the institutional label of the authority before whom it is eventually filed.
A Distinction Between Form and Fiscal Character
The judgment also contains an important lesson concerning statutory forms.
The fact that Rule 19 prescribes Form TM-M does not settle whether the completed form attracts stamp duty.
The prescribed form answers the question of how the authorisation is to be constituted for the purposes of trademark law.
It does not answer the separate question of whether the completed document is a taxable instrument.
This distinction prevents a common interpretative error: assuming that because a parent statute prescribes a document, every legal consequence associated with that document must necessarily be found within that same statutory framework.
Fiscal legislation operates independently unless an exemption is expressly provided.
The Court’s approach therefore gives primacy to the operative character of the document under the Stamp legislation.
Practical Implications for Trademark Practitioners
The judgment has immediate practical consequences for trademark agents, applicants and businesses using professional representation before the Trade Marks Registry.
First, parties should not assume that merely using the prescribed Form TM-M is sufficient from a fiscal-compliance perspective.
Second, the place of execution of the authorisation becomes relevant because stamp duty is governed by the applicable Stamp legislation.
Third, trademark agents should ensure that the authorisations on which their representation is based are appropriately stamped. Failure to address stamp requirements at the outset may create avoidable procedural objections later.
Fourth, businesses maintaining large trademark portfolios should review their existing authorisation practices, particularly where representatives act across different States and the applicable stamp-duty regimes may differ.
The respondents had specifically pointed out that stamp-duty rates can vary from State to State. The judgment consequently brings attention to a compliance issue that can otherwise remain invisible during routine trademark prosecution.
The Larger Principle: Fiscal Statutes Cannot Be Bypassed Through Terminology
At a broader level, the decision reflects a familiar but important judicial principle concerning fiscal legislation.
The Court referred to the Supreme Court decisions in Hindustan Steel Ltd. v. Dilip Construction Company and Dr. Chiranji Lal v. Haridas while emphasising the nature and purpose of stamp legislation.
The central proposition is that the fiscal consequences attached to an instrument must be determined under the legislation imposing the fiscal charge.
Accordingly, describing a document as an “authorisation” cannot, by itself, prevent the Stamp Act from applying if the document substantively creates the authority contemplated by the statutory definition of a power of attorney or an instrument.
In other words, terminology cannot defeat fiscal character.
Conclusion
The Kerala High Court’s decision in John Vadassery v. Registrar of Trade Marks & Anr. is a significant clarification at the intersection of trademark procedure and stamp law.
The Court did not hold that the Trade Marks Act itself mandates execution of a traditional power of attorney. Rather, it recognised a more nuanced proposition: the authorisation required under Section 145 and Rule 19, although described as an “authorisation”, is legally an instrument conferring authority upon the trademark agent to act for and represent the principal. Its liability to stamp duty must therefore be determined under the applicable Stamp legislation.
The decision is particularly valuable because it separates two questions that are easily conflated. The Trade Marks Act determines who may represent a party and in what prescribed manner. The Stamp Act determines whether the instrument creating that authority attracts fiscal liability.
For trademark practitioners, the message is clear. A Form TM-M authorisation is not merely an administrative formality. It is a legally operative instrument with consequences extending beyond the immediate procedural requirements of the Trade Marks Registry. In an increasingly professionalised trademark prosecution system, where agents routinely undertake acts capable of affecting valuable intellectual property rights, the legal character of the authorisation cannot be reduced to its title. Where the document creates the authority to act on behalf of another, the law will look to its substance—and the fiscal consequences may follow accordingly.